When the bank doesn’t fit the deal, we find the lender who does.
Bank, alternative and private mortgages across Ontario. Self-employed, unconventional income, tight timelines or tricky properties: plain English, clear options, no surprises.
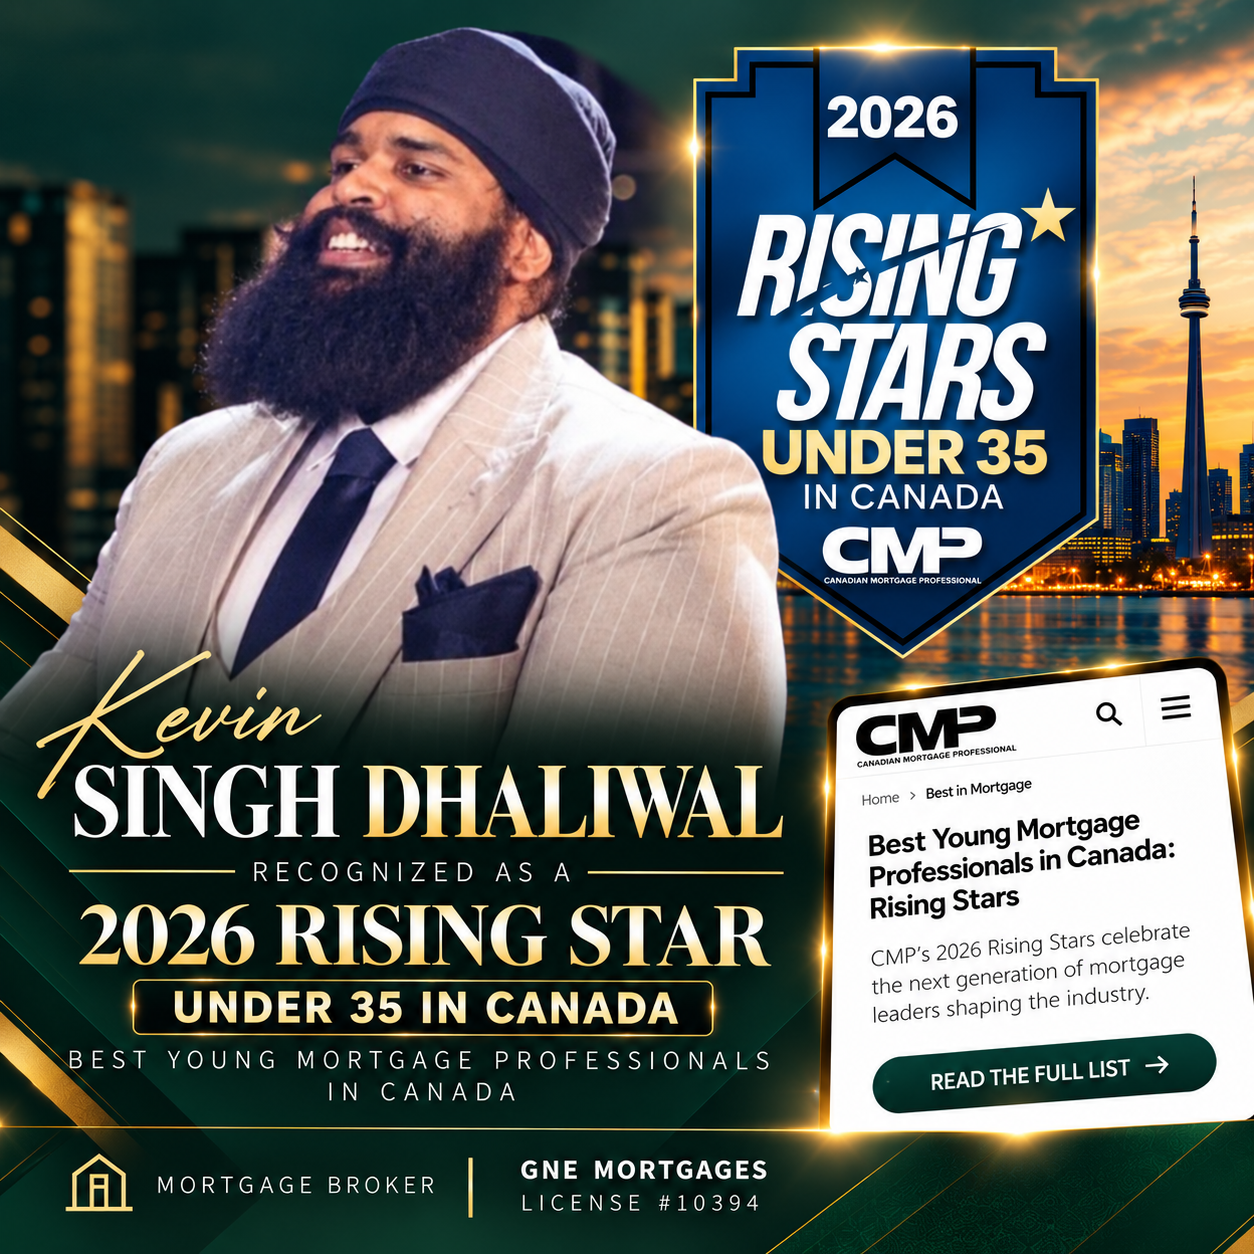
 2026 CMP Rising Star
Licensed Mortgage Broker
Residential, commercial and private
Access to Canada’s major banks, alternative and private lenders
Not sure where to start?
Find your best path in three questions.
Buying, refinancing, renewing, self-employed or turned down by the bank. Answer three quick questions and we’ll point you to the right option.
What do you need help with?
How do you earn your income?
Has a bank already said no, or is timing tight?
How it works
Five clear steps. No guessing what happens next.
From the first call to the day you get the keys, you always know where your file stands and what comes next.
What we do
Mortgages built around your situation, not a bank's checklist.
Private lending
Access to private lenders when you need a different path.
Private lending is the core of Kevin's practice. Through his network of private lenders, he arranges first and second mortgages and private HELOCs across all of Ontario, including commercial, rural and vacant land.
Real files, real outcomes
Deals the bank wouldn't do.
A few recent situations and how they were solved.
A young family facing power of sale
- The situation
- A couple with a newborn had fallen behind and their home was already in power of sale. Their bank couldn't help.
- The solution
- Kevin arranged a private mortgage through his lender network to pay out the arrears and give them time to get back on track.
An appraisal came in well short before closing
- The situation
- A buyer's appraisal with another lender came in far below the purchase price, leaving a large shortfall with closing approaching.
- The solution
- Kevin restructured the financing with a different lender and worked the file through to the finish.
A business line of credit for a growing company
- The situation
- A business owner needed a line of credit to fund growth, with income that didn't fit a bank's standard checklist.
- The solution
- Kevin packaged the file around how the business actually earns and matched it with the right lender.
Details have been changed to protect client privacy. Every situation is different and approval is not guaranteed.
Meet your broker
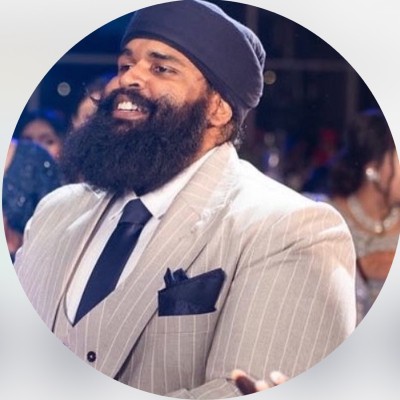
Kevin Singh Dhaliwal
Kevin is a licensed mortgage broker based in Mississauga, serving clients across Ontario. His practice focuses on the files banks find difficult: self-employed borrowers, private and second mortgages, commercial property and tight timelines. Named a 2026 CMP Rising Star.
What clients say
100+ five-star Google reviews.


Questions
Frequently asked questions
What is a private mortgage, and who is it for?
A private mortgage is a loan from a private lender instead of a bank. It is often used when a bank says no or the timing is tight: self-employed income, credit challenges, power of sale, unique properties or short-term bridge financing. It usually costs more than a bank mortgage, so it is typically a short-term solution with a plan to move back to a traditional lender.
Is Kevin a lender?
No. Kevin is a licensed mortgage broker. He works with banks, alternative lenders and private lenders to find the option that fits your situation, rather than selling one lender's products.
Can I get a mortgage if I'm self-employed?
Yes. Many lenders have programs for business owners and self-employed borrowers. The right lender depends on how your income is reported, how long you have been in business and the documents you have.
How much can I borrow with a private mortgage?
Private first mortgages typically go up to 80% of the property value, with some lenders going to 85%. Private second mortgages typically go up to 80% combined. Rural, vacant land and commercial properties usually qualify for less.
What is a private HELOC?
A private home equity line of credit lets you borrow against your home as you need it. Many are fully open with no prepayment penalty and no minimum draw, with terms from 1 to 5 years.
Do you only work in Mississauga and the GTA?
No. Kevin is based in Mississauga and helps clients across Ontario, including rural and commercial properties.
What documents will I need?
Usually photo ID, proof of income (pay stubs and T4s, or notices of assessment and business financials if self-employed), details of the property, and your current mortgage statement if you own. Kevin will tell you exactly what your file needs.
Got a deal the bank won't touch? Let's look at it.
A 15 minute call is usually enough to know your options.